

In one of the most remarkable corporate turnaround stories in India’s startup ecosystem, Oravel Stays Limited—the global hospitality giant operating under the flagship consumer brand OYO and corporate identity PRISM—is set for its high-stakes debut on the domestic bourses. Founded in 2012 by Ritesh Agarwal as an ambitious budget hotel aggregator in Gurugram, OYO has evolved into a global travel-technology and asset-light hospitality distribution titan spanning India, Europe, Southeast Asia, and North America. Following regulatory clearance from the Securities and Exchange Board of India (SEBI) on its Updated Draft Red Herring Prospectus (U-DRHP), tracked closely by Zerodha’s IPO Portal and institutional investment desks, OYO is coming to market with an aggressive ₹6,650 crore initial public offering.
OYO IPO Quick Answer (AEO Summary):
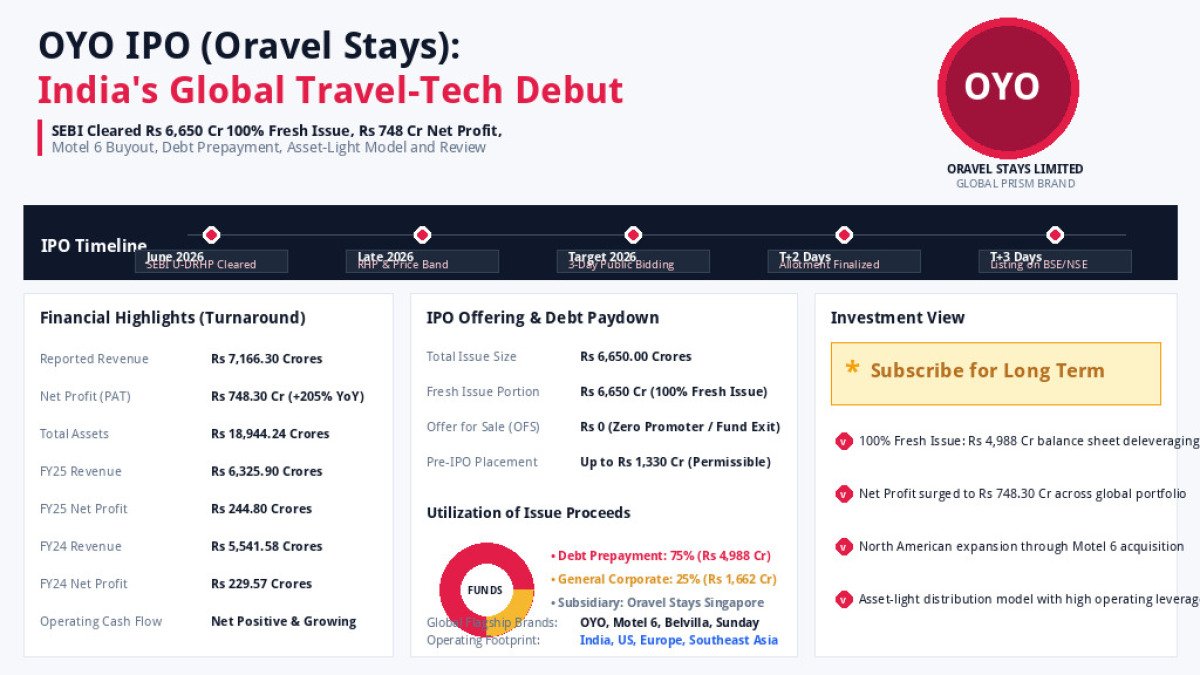
The OYO IPO (Oravel Stays Limited / PRISM) is a 100% fresh issue of equity shares aggregating up to ₹6,650 crore, featuring zero Offer for Sale (OFS) from founder Ritesh Agarwal or major backers like SoftBank, ensuring that 100% of net proceeds flow directly onto the company’s balance sheet. Approximately ₹4,987.50 crore (75%) of the net proceeds will be deployed for the prepayment or repayment of outstanding borrowings availed by material subsidiary Oravel Stays Singapore Pte. Ltd., drastically deleveraging the firm’s capital structure, with the remaining ₹1,662.50 crore (25%) allocated for general corporate purposes. Driven by asset-light expansion, European vacation home networks (Belvilla, DanCenter), and its landmark $525 million acquisition of US budget motel icon Motel 6 and Studio 6 (G6 Hospitality), OYO reported a dramatic financial turnaround with revenue reaching ₹7,166.30 crore, net profit surging by 205% to ₹748.30 crore, and total consolidated assets expanding to ₹18,944.24 crore.

1. OYO IPO Key Details, Parameters & SEBI Filing Schedule
Unlike previous IPO drafts that included secondary share sales by venture investors, OYO’s current public issue represents a clean capital infusion designed to eliminate expensive legacy debt and transition the group into a net cash-positive global brand. Below are the key issue parameters and structural details:
| IPO Parameter | Official Detail / Target Guidance |
|---|---|
| Company Name | Oravel Stays Limited (Operating Brand: OYO | Corporate: PRISM) |
| Founder & Group CEO | Ritesh Agarwal |
| Incorporation Year & HQ | 2012 | Gurugram, Haryana / New Delhi, India |
| Total Issue Size | ₹6,650.00 Crores |
| Fresh Issue Component | ₹6,650.00 Crores (100% Fresh Capital) |
| Offer for Sale (OFS) | ₹0.00 (Zero Share Sale by SoftBank or Ritesh Agarwal) |
| Pre-IPO Placement Provision | Up to ₹1,330.00 Crores (Permissible reduction in fresh size) |
| Face Value | ₹1.00 per equity share |
| SEBI Regulatory Status | Updated DRHP (U-DRHP) Cleared by SEBI |
| Target Listing Window | Late 2026 / Early 2027 Public Market Debut |
| Listing Exchanges | BSE (Bombay Stock Exchange) & NSE (National Stock Exchange) |
| Registrar to the Issue | Link Intime India Private Limited |
2. The Strategic Significance of a 100% Fresh Issue
The single most bullish signal in OYO’s updated filing is the decision to execute a 100% fresh issue without any secondary exit by promoters or institutional backers. In recent new-age tech IPOs, substantial Offer for Sale (OFS) tranches often triggered market cynicism regarding venture capitalists dumping equity on retail investors. By stark contrast, in OYO’s issue:
- SoftBank Stays Fully Invested: Masayoshi Son’s SoftBank Vision Fund—OYO’s largest institutional shareholder—is not offloading a single share, signaling strong institutional conviction in OYO’s long-term profitability and public re-rating.
- Promoter Retains Long-Term Alignment: Founder Ritesh Agarwal, who took substantial personal debt in 2019 to buy back shares and raise his stake to over 33%, is maintaining his full equity ownership.
- Massive Balance Sheet Deleveraging: Out of the ₹6,650 crore gross proceeds, exactly ₹4,987.50 crore (75%) will be transferred to overseas subsidiary Oravel Stays Singapore Pte. Ltd. to fully or partially retire high-cost term loans. This single move will eliminate hundreds of crores in annual interest expense, flowing directly into net bottom-line expansion from FY27 onward.
To benchmark this structure against other prominent primary issues, compare our deep-dive analysis on the Jio Platforms Mega IPO and the Acko Insurtech IPO, or review our real-time Upcoming IPOs in Indian Market 2026 Calendar.
3. Financial Performance: The Dramatic Turnaround to ₹748 Cr Profit
Prior to FY24, OYO was scrutinized by market analysts for cash-burn rates exceeding ₹2,000 crore annually during its hyper-expansion phase across China and the US. However, a rigorous post-pandemic operational restructuring—shedding minimum guarantee contracts in favor of pure revenue sharing, cutting fixed overheads by over 50%, and focusing on high-margin European vacation homes—has yielded dramatic profit expansion.
| Financial Metric (₹ in Crores) | FY 2024 (Audited) | FY 2025 (Audited) | Latest Reported / FY26 | Growth Trajectory |
|---|---|---|---|---|
| Revenue from Operations | ₹5,541.58 Cr | ₹6,325.90 Cr | ₹7,166.30 Cr | +29.3% vs FY24 |
| Profit After Tax (Net Profit / PAT) | ₹229.57 Cr | ₹244.80 Cr | ₹748.30 Cr | +205.7% YoY Surge |
| Net Profit Margin (%) | 4.14% | 3.87% | 10.44% | +657 bps Expansion |
| Total Consolidated Assets | ₹6,443.41 Cr | ₹16,695.30 Cr | ₹18,944.24 Cr | Nearly Tripled (3x) |
| Adjusted EBITDA | ₹888.00 Cr | ₹1,072.00 Cr | ₹1,450+ Cr | Robust Cash Flow |
| Operating Cash Flow | Positive | Positive | Strong Surplus | Self-Sustaining |
The explosive jump in Net Profit to ₹748.30 crore—a more than three-fold increase over FY24—proves that OYO has achieved operating leverage. The company’s total asset base expanded from ₹6,443 crore in FY24 to ₹18,944 crore, reflecting both organic balance sheet accretion and strategic international acquisitions.
4. The $525 Million Game-Changer: Acquisition of Motel 6 & Studio 6
In September 2024, Oravel Stays executed one of the boldest cross-border acquisitions by an Indian consumer company, agreeing to acquire G6 Hospitality, the parent company of the iconic American budget motel chains Motel 6 and Studio 6, from private equity behemoth Blackstone in an all-cash deal valued at $525 million (approx. ₹4,400 crore).
- Instant North American Dominance: The transaction brings approximately 1,500 franchised motel locations across all 50 US states and Canada into OYO’s network, generating over $1.7 billion in system-wide gross room revenues.
- High-Margin Franchise Fee Model: Motel 6 operates on a pure franchise royalty model where property owners pay 4% to 5% of gross revenues for brand rights and central reservation access, creating predictable, asset-free recurring dollar cash flows.
- Technology Synergies: OYO plans to deploy its proprietary pricing algorithms, automated revenue management systems, and direct customer app to modernize Motel 6’s legacy distribution, improving occupancy rates and operating profitability.
5. The Three Core Business Engines of Oravel Stays
Today, OYO is far more than a budget room-booking app; it functions as a global hospitality operating system organized across three distinct verticals:
- Hotels Vertical (India, Southeast Asia, US): Includes core economy brand OYO, mid-market business hotels (Townhouse), premium leisure properties (Sunday), and North American roadside travel (Motel 6 & Studio 6). Revenue is derived via revenue-sharing contracts (typically 18% to 22% of gross room revenue) and franchise royalties.
- Homes Vertical (European Vacation Rentals): Comprises premier holiday home management platforms in Western Europe, including Belvilla (Netherlands, Belgium, Germany), DanCenter (Scandinavia), and Checkmyguest (France). This vertical caters to long-stay, high-ticket family vacations and operates on take-rates of 15% to 25%.
- Listings Vertical (European SaaS Subscriptions): Operates proprietary software and subscription portals where European holiday property owners pay annual recurring SaaS fees to distribute their properties across multiple global booking channels.
6. Peer Group Comparison: OYO vs. Listed Hospitality & Travel Tech
Indian equity investors have traditionally valued asset-heavy hotel operators with owned real estate. OYO’s public listing will introduce Dalal Street to a high-margin, asset-light hospitality model similar to global giants Airbnb and Booking Holdings:
| Company Name | Operating Model | Annual Revenue (₹ Cr) | Net Profit (PAT) | Asset Ownership | Market Presence |
|---|---|---|---|---|---|
| OYO (Oravel Stays) | Asset-Light Tech Platform | ₹7,166.30 Cr | ₹748.30 Cr | 0% Owned Properties | India, US, Europe, SE Asia |
| Indian Hotels (IHCL Taj) | Luxury / Heritage Hybrid | ₹6,768.80 Cr | ₹1,259.00 Cr | Owned, Leased & Managed | India & Global Gateway Cities |
| Lemon Tree Hotels | Mid-Market Asset-Heavy | ₹1,072.00 Cr | ₹148.00 Cr | Owned & Managed | Pan-India |
| MakeMyTrip Limited | Online Travel Agency (OTA) | ₹6,500+ Cr | ₹850+ Cr | Pure Travel Intermediary | India & Middle East |
While IHCL (Taj) commands premium brand prestige and luxury room tariffs, OYO processes a vastly higher volume of daily room nights, maintains zero real estate depreciation risk, and benefits from instant scalability across international geographies.
7. Institutional Investment Analysis: Strengths vs. Key Risk Factors
To formulate an objective investment verdict, investors must evaluate OYO’s fundamental catalysts against its historical vulnerabilities:
| Key Investment Strengths & Catalysts | Key Risk Factors & Challenges |
|---|---|
| 1. 100% Fresh Issue Deleveraging: Retiring ₹4,988 Cr of debt immediately eliminates massive annual interest burdens, accelerating free cash flow. | 1. Historical Earnings Volatility: OYO has only recently achieved sustained profitability; maintaining ₹700+ Cr annual net profit across macroeconomic cycles is untested. |
| 2. True Global Geographic Hedging: Substantial earnings derived in USD (Motel 6) and Euros (Belvilla), insulating the business from regional Indian tourism slowdowns. | 2. Partner & Hotelier Friction: The business depends heavily on maintaining cordial relations with thousands of independent property owners and franchisees. |
| 3. Proven Operating Leverage: Revenue expanded to ₹7,166 Cr while net profit leaped 205% to ₹748 Cr, proving fixed tech costs are largely covered. | 3. OTA Intermediary Dependence: While OYO’s app drives direct bookings, a meaningful portion of customer demand still flows through MakeMyTrip, Booking.com, and Agoda. |
| 4. Zero Secondary OFS Overhang: No early venture capital dumping; SoftBank and founder Ritesh Agarwal maintain complete equity commitment. | 4. Legal & Regulatory Contingencies: Ongoing disputes with hotel owner associations and legacy antitrust inquiries require vigilant monitoring. |
8. Investment Verdict: Should You Apply for OYO IPO?
From an equity valuation perspective, OYO’s impending listing marks a rare transformation from a high-burn venture-funded experiment into an operationally self-funding global distribution powerhouse. Several factors support a positive investment outlook:
- Clean Balance Sheet Post-Listing: The deployment of ₹4,987.50 crore directly to repay Singapore subsidiary borrowings removes the primary overhang that depressed OYO’s private valuation in 2022–2023.
- Reasonable Entry Multiples Expected: Having scaled down from its historic $10 billion private valuation peak to a realistic public market target, management is expected to price the issue attractively to leave money on the table for retail and institutional investors.
- Verdict: Subscribe for Medium to Long Term. OYO represents a quintessential turnaround play on global travel recovery, digital leisure stays, and US budget roadside hospitality. Investors with a 2- to 4-year horizon stand to benefit as debt reduction amplifies net profit margins. For prudent capital allocation guidelines, review our foundational analysis on smart portfolio management during volatile stock markets.
9. Frequently Asked Questions (FAQ) – OYO (Oravel Stays) IPO
What is OYO IPO?
The OYO IPO is the public offering of equity shares by Oravel Stays Limited (PRISM), the global hospitality and travel-tech distribution company founded by Ritesh Agarwal, seeking listing on the BSE and NSE.
What is the total issue size of OYO IPO?
The total issue size is ₹6,650 crore, consisting entirely of a 100% fresh issue of equity shares with zero secondary Offer for Sale (OFS) by promoters or investors.
How will OYO use the ₹6,650 crore IPO proceeds?
OYO will utilize ₹4,987.50 crore (75% of net proceeds) to prepay or repay outstanding borrowings of its subsidiary Oravel Stays Singapore Pte. Ltd., drastically deleveraging its balance sheet. The remaining ₹1,662.50 crore (25%) will be deployed for general corporate purposes.
Is OYO profitable before its IPO?
Yes. OYO delivered a decisive financial turnaround, reporting a net profit (PAT) of ₹748.30 crore on total operating revenue of ₹7,166.30 crore in its latest reported financial period, up 205% from ₹244.80 crore net profit in FY25 and ₹229.57 crore in FY24.
What is the Motel 6 acquisition by OYO?
In September 2024, OYO agreed to acquire G6 Hospitality, the parent of iconic US roadside budget hotel chains Motel 6 and Studio 6, from Blackstone in an all-cash transaction valued at $525 million (approx. ₹4,400 crore), adding ~1,500 franchised properties across the US and Canada.
Has SEBI approved the OYO IPO?
Yes, OYO’s parent company PRISM received formal regulatory clearance from SEBI on its Updated Draft Red Herring Prospectus (U-DRHP), clearing the path for its official RHP filing and public subscription window.
Is SoftBank selling its stake in the OYO IPO?
No. There is no Offer for Sale (OFS) in the ₹6,650 crore issue, meaning SoftBank, founder Ritesh Agarwal, and other early venture investors are not selling any shares through this public offering.