Office Address
14, Residency Road, Udaipur, Rajasthan 313001
Office Address
14, Residency Road, Udaipur, Rajasthan 313001
NEW DELHI: Building a contingency cushion is the cornerstone of household financial stability, yet choosing the right vehicle to hold liquid cash often creates confusion among retail investors. Determining the best avenues for an emergency fund in india safe options requires evaluating immediate redemption access, capital protection, and tax efficiency rather than chasing double-digit alpha. While sudden health crises, job disruptions, or urgent repairs demand instant cash flow, deploying contingency reserves into volatile or lock-in instruments can trigger steep exit penalties or catastrophic capital erosion during market drawdowns.
⚡ Quick Highlights: Emergency Fund in India: 5 Safe Options & 4 to Avoid
The foundational objective of an emergency fund is uncompromised liquidity and absolute capital preservation. A well-constructed contingency reserve should ensure that cash is available within seconds or hours, without relying on personal loans, credit card debt, or liquidating long-term investments. Households looking to reduce overhead costs, much like families evaluating energy savings through PM Surya Ghar Muft Bijli Yojana Rajasthan: 2026 Subsidy Slabs, Online Apply & Jan Aadhaar KYC Guide, find that disciplined allocation protects regular cash flow from sudden financial shocks.
The first and most accessible venue is a separate secondary savings account with a scheduled commercial bank, isolated from daily UPI spending. Keeping one to two months of basic living costs here prevents operational friction during midnight medical admissions or utility disruptions.
The second option is a sweep-in fixed deposit (auto-sweep FD) linked directly to your primary operating account. Excess balances above a specified threshold are converted into term deposits earning higher interest rates, yet if an ATM withdrawal or cheque exceeds the savings balance, the bank automatically breaks the required FD tranche without levying premature withdrawal penalties on the untouched portion.
Thirdly, liquid mutual funds investing in sovereign debt, treasury bills, and high-grade corporate commercial paper with maturities of up to 91 days serve as an excellent vehicle for months four through twelve of your reserve. Leading fund houses provide instant redemption facilities allowing up to ₹50,000 or 90% of folio value to hit your bank account within minutes via IMPS.
Fourth on the safe list are overnight debt mutual funds. These schemes deploy capital into securities that mature in a single business day, virtually eliminating interest rate risk and credit default exposure, making them ideal for ultra-conservative investors.
Lastly, 91-day Government Treasury Bills (T-Bills), purchased directly through the RBI Retail Direct platform, offer pure sovereign credit risk backing. While secondary liquidity requires a functional market trade, holding them in staggered maturities guarantees non-volatile yield and zero principal default risk. (Also read: PM Surya Ghar Muft Bijli Yojana Rajasthan: 2026 Subsidy Slabs, Online Apply & Jan Aadhaar KYC Guide).
“An emergency reserve is an insurance policy for your financial sanity, not an investment vehicle meant to generate market-beating returns. Liquidity and capital stability must always override yields.” — Ramanathan Iyer, Certified Financial Planner, Mumbai
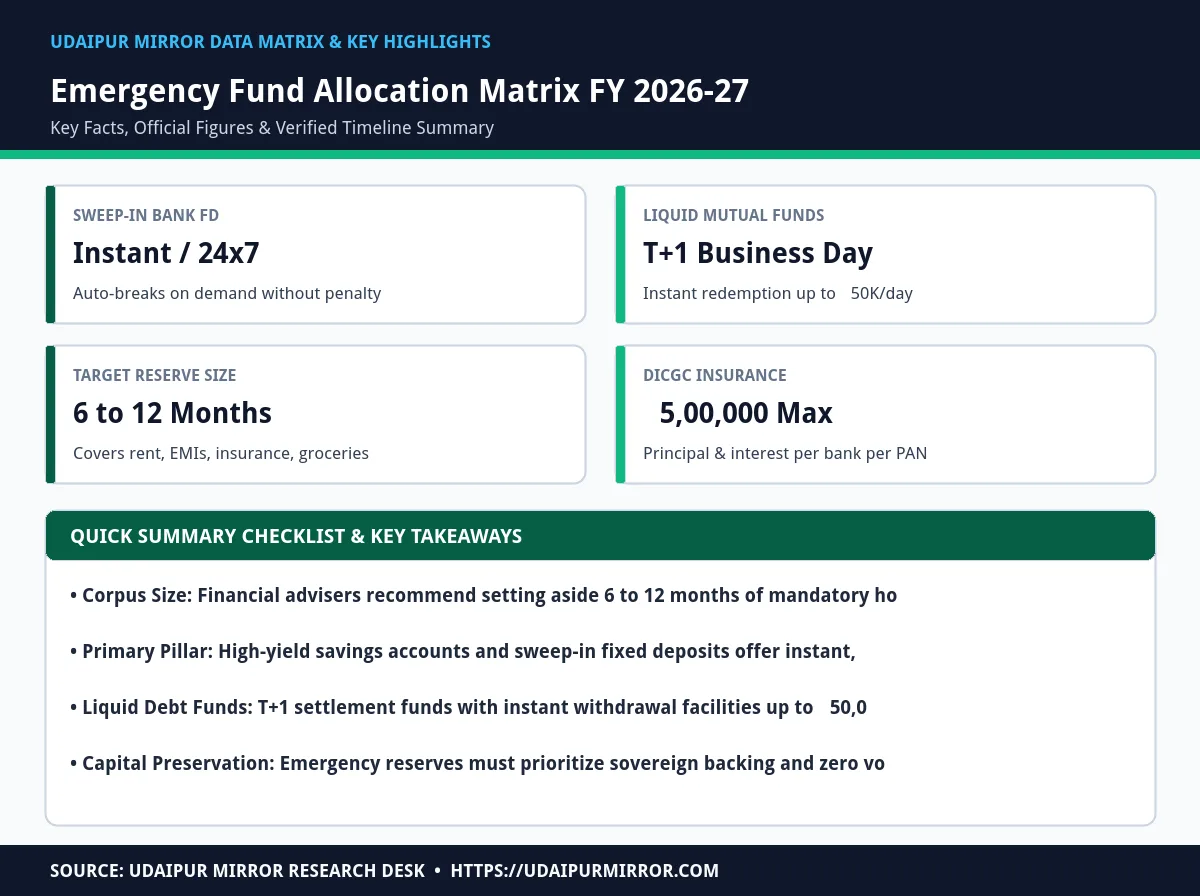
When structuring your contingency reserves in FY 2026-27, diversification across immediate and near-cash instruments balances accessibility with modest post-tax earnings. The table below outlines key parameters across standard Indian debt vehicles:
| Instrument | Indicative Yield (FY 2026-27) | Redemption Timeline | Risk Grade | Ideal Allocation Share |
|---|---|---|---|---|
| High-Yield Savings Account | 3.00% – 6.50% | Immediate (ATM / UPI / IMPS) | Very Low (DICGC Insured) | 20% – 30% |
| Sweep-in Fixed Deposit (Auto-Sweep) | 6.50% – 7.10% | Instant via net banking or debit card | Very Low (DICGC Insured) | 30% – 40% |
| Liquid Debt Mutual Funds | 6.25% – 6.85% | T+1 Business Day (Instant ₹50K) | Low (Credit & Duration Risk) | 25% – 35% |
| Overnight Mutual Funds | 5.90% – 6.20% | T+1 Business Day | Minimal (1-day maturity) | 10% – 20% |
| Short-Term Treasury Bills (91-Day) | 6.30% – 6.65% | Secondary market trade / maturity | Sovereign (Zero Credit Risk) | Optional (Hold to maturity) |
Many retail investors make the grave mistake of seeking capital growth on their contingency reserves, mistakenly believing that keeping money in stable cash instruments causes an unacceptable loss to inflation. While forward-looking investments and advanced technologies captivate the market—as seen with cutting-edge automotive developments detailed in Elon Musk’s Tesla Opens Bookings in India for ‘Flying’ Roadster: Deep-Dive into SpaceX Thrusters, ₹2.5 Cr Deposit, and 2028 Launch—allocating emergency funds to high-beta avenues introduces dangerous fragility into household finances.
The most critical trap to avoid is equity mutual funds, direct stocks, and index ETFs. Equities are inherently volatile over short horizons. If a breadwinner experiences job redundancy during a macroeconomic recession, equity markets are frequently depressed simultaneously. Forcing a redemption during a 20% to 30% market correction locks in devastating permanent capital losses.
The second category to avoid is lock-in tax-saving schemes such as Equity Linked Savings Schemes (ELSS), Public Provident Fund (PPF), and National Pension System (NPS). ELSS mutual funds enforce a statutory 3-year lock-in with zero premature withdrawal provisions. PPF mandates a 15-year tenure with restricted loan facilities only after several years, making these instruments completely useless during instant medical crises.
Thirdly, investors should avoid physical gold, jewelry, and real estate. Physical ornaments suffer from high making charges, melting deductions, and significant bid-ask spreads upon immediate liquidation, while real estate takes months or years to monetize.
Lastly, high-risk credit risk funds and peer-to-peer (P2P) lending platforms must be strictly bypassed. Promising 9% to 12% yields, P2P platforms often face severe illiquidity and default waves during economic contractions, freezing investor capital indefinitely.
“When life throws a crisis, having your emergency funds trapped behind a statutory three-year lock-in or in an equity portfolio down 25% turns an operational challenge into a catastrophic financial ruin.” — Dr. Sunita Deshmukh, Senior Wealth Strategist, Bengaluru

Calculating the exact size of your emergency corpus requires a structured audit of essential household obligations. Rather than relying on arbitrary figures, financial planners calculate mandatory baseline outflows: rent or home loan EMIs, child education tuition, basic food and utilities, personal vehicle loans, and life and health insurance premiums.
For salaried professionals working in stable multinational firms or civil services with dual household incomes, maintaining 6 months of baseline expenses is generally adequate. However, for independent consultants, gig-economy workers, startup employees, or single-earner households with dependent parents, financial security necessitates a larger buffer of 9 to 12 months of mandatory outflows.
It is vital to review and recalibrate this emergency reserve annually. If your housing rent increases, your lifestyle expenses rise, or you take on a new home renovation EMI, your emergency fund balance must be systematically increased to match your expanded monthly run rate. (Also read: Devi Bhagwat Katha Concludes in Udaipur with Mahapuja of 501 Specially-Abled Girls).
Understanding taxation on short-term debt instruments is critical for maximizing net take-home liquidity. Under current tax laws applicable for FY 2026-27, all capital gains emerging from debt mutual funds (schemes with not more than 35% equity exposure) acquired on or after April 1, 2023, are treated as short-term capital gains (STCG) regardless of holding tenure.
These gains are added directly to the taxpayer’s total income and taxed at applicable individual income tax slab rates under the selected regime. Similarly, interest earned on savings bank accounts is taxable under ‘Income from Other Sources’, though Section 80TTA provides a deduction of up to ₹10,000 for non-senior citizens under the Old Tax Regime. In contrast, under the default New Tax Regime, no Section 80TTA or 80C deductions apply, making slab-based taxation uniform across bank fixed deposits and liquid funds.
Financial experts recommend maintaining between 6 to 12 months of non-negotiable living expenses, which includes house rent, active loan EMIs, utility bills, food expenses, school fees, and recurring insurance premiums.
No. Equity funds fluctuate with broader market cycles and can lose 20% to 30% of their value during economic downturns, precisely when an investor might face layoffs or medical emergencies, forcing them to sell at a severe loss.
Yes, especially sweep-in fixed deposits linked to your bank account. Deposits in scheduled commercial banks are insured up to ₹5 lakh per depositor across principal and interest by the DICGC, a wholly-owned subsidiary of the Reserve Bank of India.
Most leading asset management companies provide an instant redemption facility for liquid funds that transfers up to ₹50,000 or 90% of your folio value to your registered bank account within minutes via IMPS. Standard redemptions are processed on a T+1 business day timeline.
Add Udaipur Mirror as a preferred source on Google to see more of our travel guides in your AI overviews.


[…] and Mewar Temple Darshan Guide 2026: Timings, VIP Rules, and Travel Routes 2 seconds ago ⚡ Articles Where to Keep Your Emergency Fund in India: 5 Safe Instruments and 4 High-Risk Traps to Av… Articles PM Surya Ghar Muft Bijli Yojana Rajasthan: 2026 Subsidy Slabs, Online Apply & Jan […]
[…] and Mewar Temple Darshan Guide 2026: Timings, VIP Rules, and Travel Routes 2 hours ago ⚡ Articles Where to Keep Your Emergency Fund in India: 5 Safe Instruments and 4 High-Risk Traps to Av… Articles PM Surya Ghar Muft Bijli Yojana Rajasthan: 2026 Subsidy Slabs, Online Apply & Jan […]