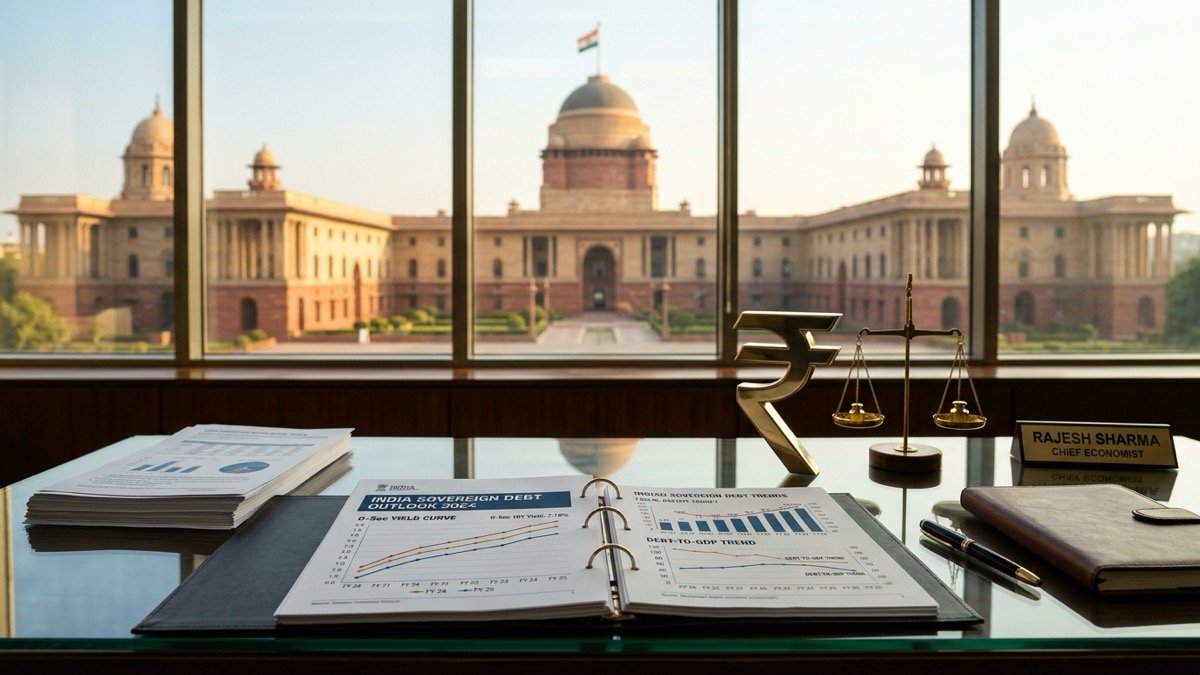
Few economic indicators provoke as much spirited political debate, investor scrutiny, and public anxiety as the sovereign public debt on Indian government. Critics frequently point to headline figures crossing ₹175 lakh crore to warn of an impending debt trap, while government economists and international credit rating agencies point to India’s blistering nominal GDP growth and low external exposure as proof of robust fiscal resilience. To separate sensationalist rhetoric from macroeconomic reality, one must examine not just how much India owes, but to whom it owes, in what currency, at what interest rate, and how those borrowed funds are being deployed.
As the Indian economy powers through 2026 as the world’s fastest-growing major economic engine, understanding the anatomy of its General Government Debt (combining both Central and State liabilities) is essential for investors, taxpayers, and policymakers alike. This comprehensive analysis breaks down the total quantum of debt, the trajectory of the debt-to-GDP ratio, the vital difference between internal and external loans, the true burden of annual interest payments, an in-depth historical comparison of how debt was taken between 2004 and 2026, and why India remains fundamentally insulated from emerging market sovereign debt crises.
⚡ Key Financial Metrics: Indian Public Debt at a Glance
Total General Government Debt: Approximately ₹176–180 Lakh Crore (US$ 2.15–2.2 Trillion).
Debt-to-GDP Ratio: Consolidating around 81.5% to 82.0% (down from the pandemic peak of 89.6% in FY21).
Central Government Share: Approximately 55.5% to 56.5% of GDP.
State Governments Share: Approximately 27.0% to 28.0% of GDP.
Domestic Currency Shield: Over 95% of India’s public debt is internal, denominated in Indian Rupees (INR).
External Sovereign Debt: Less than 5% of total debt, primarily comprised of long-term concessional loans from multilateral institutions (World Bank, ADB, JICA).
The Anatomy of Indian Public Debt: What Does the Government Owe?
In macroeconomic accounting, the total debt on Indian government is measured as General Government Debt, which combines the liabilities of the Union Government and all 28 State Governments (net of inter-governmental transactions). The portfolio is structured into three primary tiers:
1. Internal Debt (Market Borrowings & G-Secs)
Internal debt represents the overwhelming majority—over 95%—of India’s total sovereign liabilities. Managed directly by the Reserve Bank of India (RBI) acting as the government’s debt manager, internal debt is raised through transparent institutional mechanisms:
Dated Government Securities (G-Secs): Long-term sovereign bonds with maturities stretching from 5 to 50 years. These instruments carry fixed semi-annual coupon rates and are subscribed to by domestic banks, insurance giants (like LIC), pension funds (EPFO), and mutual funds.
Treasury Bills (T-Bills): Short-term zero-coupon debt instruments issued with 91-day, 182-day, and 364-day tenors to manage temporary mismatches in the government’s cash flows.
Sovereign Green Bonds (SGrBs): Specialized debt issued to fund climate resilience, public mass transit, and renewable energy infrastructure.
2. Public Account Liabilities (Small Savings & Provident Funds)
Beyond market-traded bonds, the central government borrows from its internal Public Account. This includes collections from the National Small Savings Fund (NSSF)—comprising popular household savings like Public Provident Fund (PPF), National Savings Certificates (NSC), Sukanya Samriddhi Yojana, and postal deposits. These liabilities are domestic, stable, and not subject to market volatility.
Unlike countries such as Sri Lanka, Pakistan, Argentina, or Turkey, India does not issue sovereign foreign-currency commercial bonds on Wall Street or in London. The external sovereign debt on the Indian government is remarkably small—accounting for less than 3% of GDP and under 5% of total public debt.
Crucially, this external credit is almost entirely concessional borrowing from multilateral development banks—such as the International Bank for Reconstruction and Development (IBRD / World Bank), the Asian Development Bank (ADB), and the Japan International Cooperation Agency (JICA). These loans carry repayment horizons spanning 20 to 30 years with interest rates well below commercial market rates.
Historical Comparison: How the Government Took Debt from 2004 to 2026
To truly grasp the trajectory of sovereign borrowing, one must analyze the evolution of government debt across two distinct political and economic regimes: the UPA Era (2004–2014) under Dr. Manmohan Singh and the NDA Era (2014–2026) under Narendra Modi. The fundamental contrast lies not merely in nominal figures, but in how debt was incurred, how transparently it was accounted for, and whether borrowed money was consumed as operational subsidies or transformed into capital assets.
1. The 2004–2014 Era: The Boom Years, Fiscal Stimulus & Off-Budget Borrowings
When the UPA government took office in May 2004, Central Government debt stood at ₹17.33 lakh crore (with total General Government debt around ₹27.3 lakh crore, or 83.2% of GDP). Over the subsequent decade, public borrowing experienced two distinct phases:
Early Fiscal Consolidation (2004–2008): Aided by an unprecedented global macroeconomic boom and buoyant corporate tax collections, the implementation of the Fiscal Responsibility and Budget Management (FRBM) Act brought the Debt-to-GDP ratio down from 83.2% to a decadal low of 70.5% in FY 2007–08.
The 2008 Global Financial Crisis & Fiscal Slippage: Following the 2008 Lehman Brothers collapse, the central government paused FRBM targets and unleashed three successive fiscal stimulus packages. This era saw significant borrowing directed toward revenue consumption—including the 2008 agricultural debt waiver (₹60,000 crore), the expansion of social welfare entitlements (MGNREGA), and Sixth Central Pay Commission salary arrears.
The Practice of ‘Off-Budget’ Liabilities: To keep reported fiscal deficit figures lower on paper, the government introduced “Special Sovereign Bonds” issued directly to public sector entities in lieu of cash subsidies. Most notably, between 2005 and 2010, the government issued over ₹1.44 lakh crore of Oil Bonds to state oil marketing companies (IOCL, BPCL, HPCL) to subsidize petrol, diesel, and LPG, alongside tens of thousands of crores in Fertilizer Bonds. These debts did not appear in the headline fiscal deficit for those years, pushing repayment burdens into future decades.
Status in 2014: By March 2014, Central Government debt had more than tripled from ₹17.33 lakh crore to ₹55.87 lakh crore (an absolute increase of ₹38.54 lakh crore). Total General Government debt reached ₹68 lakh crore (~67.1% of GDP), while annual central Capital Expenditure remained modest at just ₹1.97 lakh crore.
2. The 2014–2026 Era: Budget Transparency, Pandemic Shock & The Capex Surge
From 2014 onward, the approach to sovereign debt underwent an institutional restructuring across three phases:
Phase 1: Cleansing Off-Budget Borrowings (2014–2019): The Union Ministry of Finance halted the issuance of opaque special bonds and began migrating legacy off-budget liabilities back onto the official budget ledger. Outstanding Oil Bonds were serviced transparently through budgetary appropriations, and extra-budgetary resources (EBR) raised by agencies like the Food Corporation of India (FCI) through the National Small Savings Fund (NSSF) were systematically absorbed into the formal Union Budget. Nominal Central debt expanded from ₹55.87 lakh crore in 2014 to ₹86.35 lakh crore in 2019, but because nominal GDP expanded simultaneously, the Debt-to-GDP ratio remained stable around 69% to 70%.
Phase 2: The COVID-19 Disruption (2020–2021): The pandemic induced the sharpest economic shock in post-independence history. With tax collections collapsing during lockdowns and emergency spending escalating (free food rations for 800 million citizens under PMGKAY, emergency healthcare, and MSME liquidity guarantees), the central fiscal deficit spiked to 9.2% of GDP. Total public debt jumped to over ₹121 lakh crore, pushing the General Government Debt-to-GDP ratio to a pandemic peak of 89.6% in FY 2020–21.
Phase 3: The Capital Expenditure (Capex) Revolution (2021–2026): Post-COVID, rather than returning to consumption-driven subsidies, the government anchored its borrowing strategy in productive capital infrastructure. Annual central Capex increased from ₹1.97 lakh crore in 2014 and ₹4.1 lakh crore in FY20 to a massive ₹11.11 lakh crore in FY 2024–25 and FY 2025–26—a 5.6-fold surge. Borrowed capital was invested in multi-lane national highways, railway electrification, dedicated freight corridors, new airports, and digital public infrastructure.
Status in 2026: Total General Government debt stands at approximately ₹176 to ₹180 lakh crore. However, because nominal GDP surged from ₹112 lakh crore in 2014 to over ₹330 lakh crore in 2026, the Debt-to-GDP ratio has fallen sharply from 89.6% down to ~81.5%, establishing a disciplined consolidation trajectory toward medium-term FRBM targets.
Milestone Comparison: Indian Government Debt from 2004 to 2026
The table below provides a factual, milestone-based historical comparison tracking how the scale, ratio, and nature of Indian public debt evolved over the past 22 years:
Record high Capex; global bond inclusion; 50-year long G-Secs
3. How the Mechanics of Borrowing Changed: 2004 vs. 2026
Beyond the raw numbers, the institutional mechanism of how the government borrows has undergone a profound transformation:
Debt Maturity Profile: In 2004, the average maturity of central government dated securities was under 10 years, creating continuous rollover anxiety and refinancing vulnerability. By 2026, the weighted average maturity of the sovereign portfolio has been extended to over 14.5 years, anchored by 30-year, 40-year, and ultra-long 50-year sovereign bonds that lock in favorable borrowing costs for decades.
Democratization of Debt Markets: In 2004, purchasing government securities was strictly reserved for primary dealers, commercial banks, and institutional treasuries. Today, through the RBI Retail Direct scheme, everyday retail citizens can purchase central and state government bonds directly via UPI with zero brokerage fees.
Sovereign Green Bonds: In 2004, borrowing had no environmental taxonomy. In 2026, the government regularly floats certified Sovereign Green Bonds (SGrBs) carrying a “greenium” (lower interest rate), funding clean transportation, grid battery storage, and solar parks.
Is India in Danger of a Debt Crisis? The Four Pillars of Debt Sustainability
Whenever global financial institutions or opposition commentators scrutinize the total debt on the Indian government, comparisons with defaulting nations inevitably arise. However, macroeconomic analysis confirms that India is insulated from sovereign default due to four structural pillars:
1. Sovereign Currency Denomination (Zero Foreign Currency Risk)
Countries that undergo sovereign bankruptcy (such as Argentina or Sri Lanka) fail because they borrow heavily in foreign currencies (US Dollars) from private global hedge funds. When their export earnings or foreign exchange reserves dry up, they cannot print US dollars to service their debt. India’s sovereign debt is overwhelmingly denominated in Indian Rupees (INR). Because the debt is internal, the Indian government faces virtually zero sovereign currency insolvency risk.
2. The Growth-Interest Rate Differential (g – r > 0)
The foundational mathematical rule of public debt sustainability states that as long as the nominal rate of GDP growth ($g$) exceeds the nominal average interest rate on sovereign debt ($r$), the debt-to-GDP ratio will naturally stabilize and decline over time without requiring draconian austerity. India’s nominal GDP expands at approximately 10.5% to 11.5% annually, whereas the weighted average borrowing cost on government securities hovers between 7.0% and 7.2%. This healthy positive differential ($g – r approx +3.5%$) acts as a natural economic shock-absorber.
3. A Captive, Reliable Domestic Investor Base
India’s G-Sec market does not rely on volatile foreign speculative capital. Commercial banks in India are legally mandated under the Statutory Liquidity Ratio (SLR) to park approximately 18% of their deposits in safe government securities. Additionally, conservative domestic institutional giants—including the Life Insurance Corporation of India (LIC), the Employees’ Provident Fund Organisation (EPFO), and public sector pension trusts—provide a permanent, predictable appetite for 30-year and 40-year government paper.
4. The Capital Expenditure (Capex) Paradigm Shift
Debt accumulated to fund non-productive revenue consumption (such as salaries, unmetered electricity subsidies, or cash transfers) destroys long-term fiscal health. In contrast, debt incurred to build wealth-generating infrastructure expands future GDP. Over the past five years, the Government of India has radically restructured the composition of its borrowing. Capital expenditure (Capex) has increased nearly threefold—from ₹4.1 lakh crore in FY20 to over ₹11.11 lakh crore in recent fiscal budgets.
Investing in dedicated freight corridors, expressway networks, airport expansions, and national renewable microgrids creates a documented GDP multiplier effect of 2.45x to 3.0x, ensuring that the economy generates far more productive wealth than the cost of the underlying loan.
The True Fiscal Cost: The Heavy Burden of Interest Payments
While India does not face sovereign default risk, carrying high public debt is far from cost-free. The real and pressing concern of the debt on the Indian government lies in its annual interest servicing liability:
Revenue Preemption: Interest payments on accumulated debt now consume approximately 24% to 25% of the central government’s total revenue expenditure. In absolute terms, the Union Government pays upwards of ₹11 lakh crore annually just to service past interest obligations.
Crowding Out Social Spending: When one out of every four rupees collected in tax revenue goes toward servicing interest on historic debt, public funding for primary healthcare, higher education, scientific research, and green urban infrastructure is inevitably constrained.
State-Level Fiscal Fragility: While the central government maintains strict borrowing discipline, certain state governments carry alarming debt-to-GSDP ratios exceeding 35% to 42% (notably Punjab, Kerala, and West Bengal), driven by off-budget borrowings, power distribution company (DISCOM) bailouts, and recurring populist subsidies.
Global Debt Comparison: How India Measures Against the World
To place India’s sovereign debt in global perspective, one must compare it against both advanced economies and emerging market peers using IMF Public Debt database benchmarks:
Country / Economy
General Govt Debt-to-GDP (%)
Dominant Debt Currency
Sovereign Credit Rating
Primary Fiscal Risk Profile
India
~81.5% – 82.0%
Indian Rupee (>95%)
BBB- (Positive / Stable)
High interest servicing cost relative to tax receipts
United States
~122% – 125%
US Dollar (Global Reserve)
AA+ / Aaa
Structural deficits, entitlement spending, political debt ceiling standoffs
Japan
~255% – 260%
Japanese Yen (Domestic)
A+
Aging demographic decline, ultra-low growth trap
United Kingdom
~100% – 102%
British Pound
AA
Sluggish economic growth, escalating bond yields (Gilts)
China
~83% (Official) / >110% (Augmented)
Chinese Yuan
A+ (Negative Outlook)
Hidden Local Government Financing Vehicles (LGFVs), property crash
Brazil
~86% – 88%
Brazilian Real
BB
High double-digit real interest rates, fiscal credibility slippage
Future Roadmap: Global Bond Index Inclusion & Rating Upgrades
India’s sovereign debt landscape is entering a transformative new era propelled by international integration:
JP Morgan & Bloomberg Global Bond Index Inflows: The formal inclusion of Indian Fully Accessible Route (FAR) government bonds into the JP Morgan Emerging Market Bond Index (GBI-EM) and Bloomberg EM Indices is channeling an estimated $25 to $30 billion of passive institutional capital into Indian debt markets. Because foreign funds buy rupee-denominated bonds on Indian exchanges, this diversification lowers domestic borrowing costs without exposing the sovereign to currency risks.
Pressure on Credit Rating Agencies: Sovereign rating agencies (S&P, Fitch, Moody’s) have historically retained India at the lowest investment grade bracket (BBB- / Baa3), citing high debt-to-GDP and low government revenue. However, with consistent fiscal consolidation, rapid formalization of the economy via GST, digital tax compliance, and world-beating growth, India’s case for a sovereign credit rating upgrade to BBB or higher is stronger than ever.
Frequently Asked Questions (FAQs)
How much is the total debt on the Indian Government in 2026?
The total General Government Debt (combining Central and State Governments) stands at approximately ₹176 to ₹180 lakh crore (around US$ 2.15 to 2.2 trillion), which translates to approximately 81.5% to 82% of India’s nominal GDP.
How did Indian Government debt change between 2004 and 2026?
In 2004, Central Government debt was ₹17.33 lakh crore (Debt-to-GDP: 83.2%). By 2014, it rose to ₹55.87 lakh crore (Debt-to-GDP: 67.1%), featuring off-budget Oil and Fertilizer Bonds. By 2026, Central debt reached ~₹178–182 lakh crore, but with all debt brought on-budget, annual infrastructure Capex expanding 5.6-fold to over ₹11.11 lakh crore, and the Debt-to-GDP ratio falling from its COVID peak of 89.6% down to ~81.5%.
Can India face a Sri Lanka or Pakistan-style foreign debt default?
No. Sri Lanka and Pakistan experienced sovereign crises because they borrowed heavily in US dollars from private foreign lenders and ran out of foreign exchange reserves. Over 95% of India’s public debt is internal and denominated in Indian Rupees (INR), eliminating foreign currency sovereign default risk.
What is the target Debt-to-GDP ratio under the FRBM Act?
The NK Singh FRBM Review Committee recommended a combined General Government Debt target of 60% of GDP—with 40% allocated to the Central Government and 20% to State Governments. The government is currently on a consolidation glidepath toward these benchmarks following the pandemic spike.
Why is India’s debt considered sustainable despite being over 80% of GDP?
India’s debt is sustainable because its nominal GDP growth rate (10.5%–11.5%) exceeds the average borrowing interest rate (7.0%–7.2%), a condition known as positive g – r. Additionally, sovereign debt is long-term, held by domestic institutions like LIC and commercial banks, and increasingly invested into high-multiplier infrastructure capital expenditure.
What percentage of the Union Budget goes into paying interest on debt?
Interest payments account for approximately 24% to 25% of the Central Government’s annual revenue expenditure (exceeding ₹11 lakh crore annually). While safe from default, this represents the primary economic cost of debt by consuming funds that could otherwise support social and developmental programs.
Find this guide helpful?
Add Udaipur Mirror as a preferred source on Google to see more of our travel guides in your AI overviews.
HC Ajmera
The Udaipur Mirror Editorial Bureau is an independent newsroom comprising financial analysts, investigative reporters, and regional correspondents based in Udaipur, Rajasthan. The bureau provides data-driven coverage of Indian IPOs, Dalal Street market movements, Rajasthan infrastructure, and Mewar architectural heritage, adhering strictly to SEBI compliance norms and the Press Council of India code of ethics.
[…] धाम के लिए 16 से सनातन पदयात्रा 2 hours ago ⚡ Business Debt on Indian Government: Complete Breakdown of Public Debt, Debt-to-GDP Ratio & Sust… Articles RRB Station Master Recruitment 2026: Notification Out for 1,265 Vacancies, Pay Level 6 […]


[…] धाम के लिए 16 से सनातन पदयात्रा 2 hours ago ⚡ Business Debt on Indian Government: Complete Breakdown of Public Debt, Debt-to-GDP Ratio & Sust… Articles RRB Station Master Recruitment 2026: Notification Out for 1,265 Vacancies, Pay Level 6 […]