Office Address
14, Residency Road, Udaipur, Rajasthan 313001
Office Address
14, Residency Road, Udaipur, Rajasthan 313001
NEW DELHI: As retail participation reaches unprecedented heights across the country, identifying the best investment options in india has become paramount for navigating shifting macroeconomic realities in October 2026. With dynamic market conditions driven by evolving RBI monetary policies, corporate earnings growth, and structural shifts in household savings, Indian investors are increasingly looking beyond traditional fixed-income instruments toward growth-oriented avenues like equity mutual funds, systematic investment plans (SIPs), and tax-efficient portfolio structuring.
⚡ Quick Highlights: Best Investment Options in India 2026: Top Choices Explored
For retail investors seeking inflation-beating returns, equity mutual funds operated through Systematic Investment Plans (SIPs) continue to dominate financial planning discussions. By committing a fixed amount monthly, investors benefit from rupee-cost averaging, purchasing more units when markets dip and fewer when prices rise. Financial advisors emphasize that consistency is far more critical than timing the market peak.
However, portfolio overlap remains a silent risk for many enthusiastic investors. Holding multiple SIPs across different fund houses that invest in the exact same top-tier bluechip stocks dilutes true diversification. Investors should periodically audit their portfolios to ensure holdings span various sectors, market caps, and investment styles. For those upgrading their living spaces alongside investments, exploring green energy solutions like the PM Surya Ghar Yojana can simultaneously reduce household utility overheads.
“Systematic investing removes emotional bias from financial decisions, allowing disciplined retail participants to compound wealth effectively over decades.” — Senior Portfolio Strategist, Mumbai
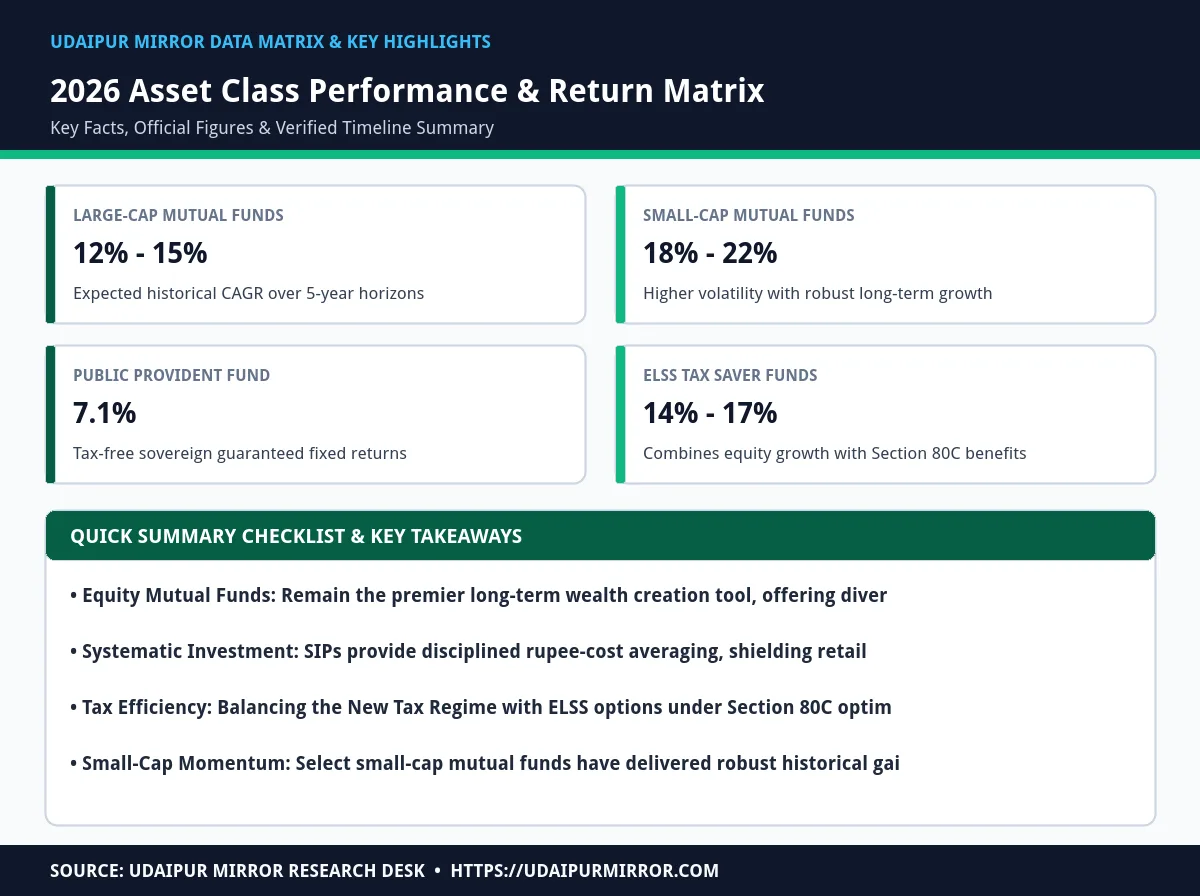
Choosing the right asset vehicle depends on your individual risk appetite, investment horizon, and financial goals. The following matrix contrasts liquidity, risk profiles, taxation, and historical performance across major instruments.
| Instrument Category | Risk Level | Average Horizon | Liquidity Profile | Tax Treatment (2026-27) |
|---|---|---|---|---|
| Equity Index & Large-Cap MFs | Moderate to High | 5+ Years | High (T+3 Redemption) | LTCG above ₹1.25L taxed at 12.5% |
| Small & Mid-Cap Mutual Funds | Very High | 7+ Years | High (T+3 Redemption) | LTCG above ₹1.25L taxed at 12.5% |
| Public Provident Fund (PPF) | Very Low | 15 Years | Low (Partial withdrawals post 7 yrs) | EEE Status (Tax-free interest & maturity) |
| ELSS Tax Saving Funds | High | 3 Years (Lock-in) | Moderate (3-year lock-in period) | Deduction under Old Regime / Capital Gains tax |
| Sovereign Gold Bonds / ETFs | Moderate | 5-8 Years | High (Exchanged traded / RBI window) | Capital gains tax exemptions on maturity for SGBs |
Tax planning remains an integral pillar of holistic personal finance. With the coexistence of the New Tax Regime and the Old Tax Regime in FY 2026-27, taxpayers must carefully calculate their deductions. While the New Tax Regime offers simplified slab rates with lower compliance friction, the Old Tax Regime continues to incentivize long-term savings through instruments like the Public Provident Fund (PPF), life insurance, and Equity Linked Savings Schemes (ELSS).
ELSS funds offer a dual advantage: potential equity-driven capital appreciation coupled with tax deductions under Section 80C, backed by a relatively short lock-in period of just three years compared to other fixed-income tax savers. Furthermore, investors prioritizing physical wellness and preventive health checks often pair their financial portfolios with robust health frameworks, drawing parallels to initiatives seen in preventive healthcare startup investments.
“Effective tax planning is not merely about minimizing annual outgo; it is about channeling saved capital into productive assets that compound over time.” — Tax & Investment Consultant
While large-cap indices provide stability, small-cap mutual funds have captured investor imagination following stellar historical performances where select funds delivered up to 20 percent gains over multi-year cycles. Nevertheless, financial planners caution that small-cap stocks experience sharper drawdowns during broader market corrections. A balanced portfolio must anchor high-beta growth assets with defensive components such as sovereign gold bonds, corporate debt funds, or senior citizen savings schemes.
Diversifying across asset classes ensures that unexpected macroeconomic shocks do not derail medium-term financial goals. Investors are advised to maintain an emergency fund equivalent to six months of essential living expenses in high-liquidity savings instruments before committing capital to volatile equity categories. (Also read: Sajjangarh Monsoon Palace & Biological Park Guide 2026: Entry Fees, Safari Timings & Sunset Point).
“True financial security stems from equilibrium—pairing aggressive growth vehicles with dependable defensive anchors.” — Chief Wealth Officer
For beginners, diversified large-cap equity mutual funds via SIPs, Public Provident Fund (PPF) for fixed income, and ELSS funds for tax savings represent the most balanced starting points.
SIPs distribute investments over time, protecting against market volatility through rupee-cost averaging. Lump sum investments work best when markets are undervalued or when large capital is available for long-term compounding.
The choice depends on your eligible deductions. If you utilize exemptions under Section 80C (like ELSS, PPF, and home loan interest), the Old Tax Regime may be beneficial; otherwise, the New Tax Regime offers simplified lower tax slabs.
Small-cap mutual funds offer high growth potential over 7 to 10-year horizons but carry significant short-term volatility. They should constitute a controlled percentage of an overall diversified portfolio.
Add Udaipur Mirror as a preferred source on Google to see more of our travel guides in your AI overviews.