Office Address
14, Residency Road, Udaipur, Rajasthan 313001
Office Address
14, Residency Road, Udaipur, Rajasthan 313001
NEW DELHI: NEW DELHI — In a welcome move for conservative retail investors seeking assured returns, fixed deposit interest rates have been officially revised upward for a popular medium-term deposit scheme. The latest financial announcement confirms that fd interest rates hiked will directly benefit individuals parking their savings in the bank’s specialized 444-day maturity plan, delivering enhanced financial gains across multiple investment brackets.
⚡ Quick Highlights: FD Interest Rates Hiked: 444-Day Plan Payouts Revised
Fixed deposit products have long remained the cornerstone of Indian household savings, offering stability against market volatility. With the latest announcement, the banking institution has fine-tuned its liability management by boosting yields on a specifically curated medium-term milestone. Savers evaluating diverse asset classes—ranging from equity instruments to fixed income—frequently rely on such tenure-specific schemes to lock in guaranteed returns before future monetary policy shifts occur. Financial advisors note that careful planning around traditional savings instruments remains vital, much like avoiding common errors when setting up retirement portfolios as highlighted in SCSS investment rules and mistakes retirees must avoid.
The revision specifically targets the 444-day milestone, striking a balance between short-term liquidity needs and long-term capital preservation. Depositors looking to allocate surplus capital can do so through digital banking channels or by visiting physical branches, ensuring seamless processing without administrative delays. (Also read: Explained: ISA's 5-Year Strategy as India Eyes Greater Global Solar Leadership).
“Our objective is to deliver competitive, predictable compounding gains to retail depositors who prioritize capital protection and stable cash flows.” — Senior Retail Banking Analyst
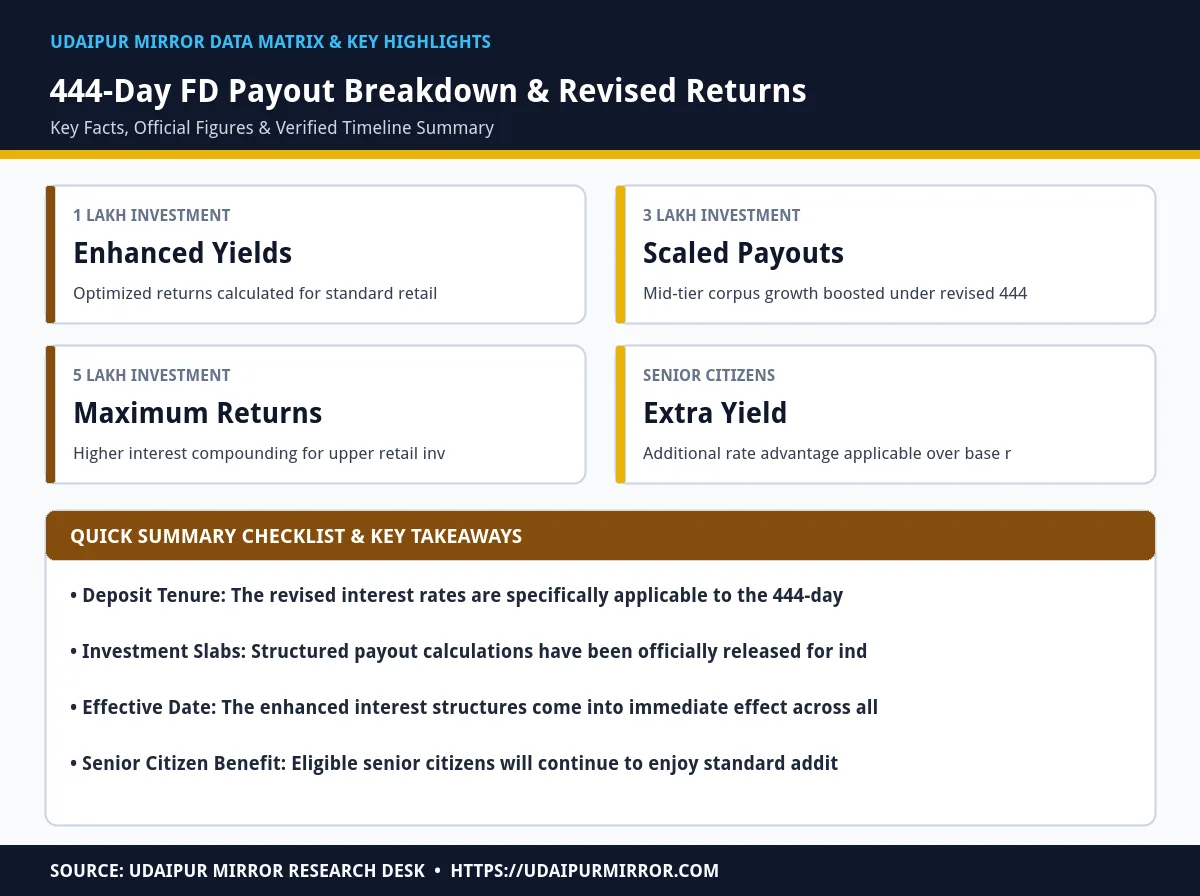
The following structured comparison illustrates the estimated maturity returns and revised earning projections for different principal amounts parked under the updated 444-day fixed deposit tenure.
| Investment Principal | Tenure Duration | Revised Interest Category | Estimated Maturity Gain Profile |
|---|---|---|---|
| ₹1,00,000 | 444 Days | Retail Standard | Enhanced compound payout with updated yield |
| ₹3,00,000 | 444 Days | Retail Standard | Proportional mid-tier growth with higher slab benefits |
| ₹5,00,000 | 444 Days | Retail Standard | Maximized retail tier return with compounding advantage |
| ₹1,00,000 (Senior) | 444 Days | Senior Citizen | Includes additional age-based interest kicker |
| ₹5,00,000 (Senior) | 444 Days | Senior Citizen | Highest absolute yield under current bank offerings |
To help retail savers quantify their exact earnings, the bank has published clear illustrative return models across three popular investment tiers: ₹1 lakh, ₹3 lakh, and ₹5 lakhs. For a baseline investment of ₹1 lakh, the revised interest computation ensures a noticeable uptick in total interest accrued upon maturity compared to standard one-year deposits. For mid-sized investors committing ₹3 lakh, the compounding effect over the 444-day period optimizes capital productivity without locking funds into multi-year commitments.
At the higher retail threshold of ₹5 lakhs, the enhanced yield significantly boosts absolute monetary gains. This tier is particularly favored by conservative investors seeking secure avenues for lump-sum windfalls. Furthermore, as traditional economic sectors adapt to modern efficiency models—akin to how businesses integrate artificial intelligence into traditional industries—banking institutions are similarly leveraging automated pricing algorithms to offer dynamic, competitive rates.
“Tiered deposit structures empower everyday savers to customize their liquidity planning while capturing higher yields on milestone tenures.” — Consumer Banking Strategist
While higher interest payouts are undeniably attractive, investors must remain cognizant of the statutory tax implications governing fixed deposits in India. Interest earned on fixed deposits is fully taxable according to the individual’s applicable income tax slab rates. Furthermore, Tax Deducted at Source (TDS) applies if total interest income across bank branches exceeds the statutory threshold of ₹40,000 for regular citizens and ₹50,000 for senior citizens within a financial year. Investors should submit Form 15G or Form 15H if their total income is below the taxable limit to prevent needless tax deduction at source.
Additionally, savers should review the premature withdrawal clauses associated with the 444-day plan. While partial or complete liquidity is generally permitted, premature closures typically attract a minor penalty fee—usually a 0.5% to 1.0% reduction in the applicable interest rate for the period the deposit actually remained with the bank. Planning cash flows to match the exact 444-day tenure ensures investors capture the full revised yield without incurring penalty deductions. (Also read: SCSS Investment Rules: 5 Mistakes Retirees Must Avoid Before Investing ₹30 Lakh).
“Always factor in tax slabs and potential premature withdrawal penalties before locking funds into specialized fixed deposit tenures.” — Tax and Investment Consultant
The revised interest rates are specifically applicable to a specialized 444-day maturity period offered by the banking institution.
Yes, eligible senior citizens receive an additional interest rate percentage over and above the newly revised baseline retail rates.
The bank has provided detailed illustrative return calculations for retail investment tiers of ₹1 lakh, ₹3 lakh, and ₹5 lakhs.
Yes, standard tax deduction at source (TDS) applies if total cumulative interest earned exceeds ₹40,000 for regular citizens or ₹50,000 for senior citizens in a financial year.
Add Udaipur Mirror as a preferred source on Google to see more of our travel guides in your AI overviews.


[…] 100-Ft Road Property Market 2026: Commercial Showroom Rates and Rental Yields 4 seconds ago ⚡ Business FD Interest Rates Hiked: Bank Increases Returns for 444-Day Plan with New Lakh-Wise Payout… Economy Explained: ISA's 5-Year Strategy as India Eyes Greater Global Solar Leadership 2 […]