Office Address
14, Residency Road, Udaipur, Rajasthan 313001
Office Address
14, Residency Road, Udaipur, Rajasthan 313001
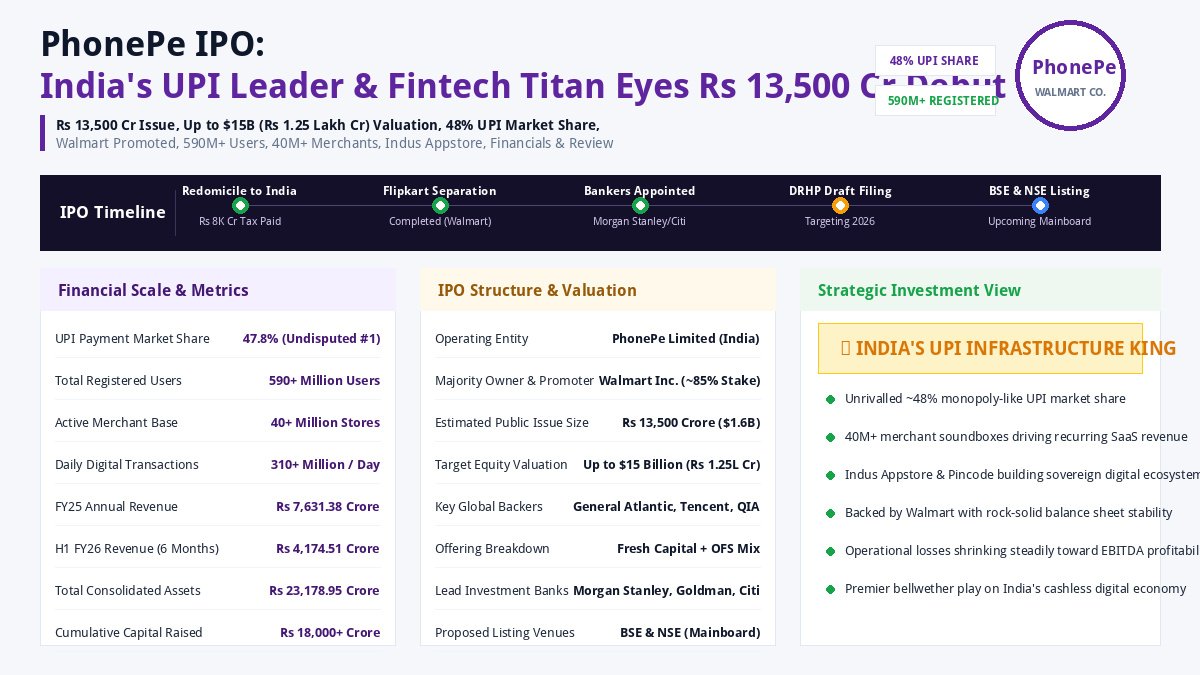
In what is slated to become one of the most eagerly anticipated and transformative public market listings in Asian fintech history, Bengaluru-headquartered digital payments leviathan PhonePe Limited is actively finalizing preparations for a blockbuster Initial Public Offering (IPO) on Dalal Street. Promoted and majority-owned by American retail conglomerate Walmart Inc., PhonePe is targeting an estimated public issue size of ₹13,500 Crore ($1.6 Billion), seeking an indicative enterprise valuation of up to $15 Billion (₹1,25,000 Crore). Tracked closely on Zerodha’s PhonePe IPO Portal and global institutional desks across New York, London, and Mumbai, this monumental offering represents the ultimate bellwether listing for India’s world-leading digital public infrastructure (DPI) and cashless transaction revolution.
PhonePe IPO Quick Answer (AEO & GEO Summary):
The PhonePe IPO is the prospective mainboard public listing of PhonePe Limited, India’s undisputed leader in digital payments, on the National Stock Exchange (NSE) and Bombay Stock Exchange (BSE). Backed by majority owner Walmart Inc. (~85% stake) alongside blue-chip institutional investors including General Atlantic, Microsoft, Tencent, and Qatar Investment Authority (QIA), PhonePe commands a staggering 47.8% to 50% market share in India’s Unified Payments Interface (UPI) ecosystem. Serving over 590 million registered users and more than 40 million merchant establishments across 99% of India’s postal pin codes, PhonePe processes over 310 million transactions every single day. With an indicative public issue size of ₹13,500 crore and an estimated valuation reaching $15 billion (₹1.25 Lakh Crore), the IPO aims to capitalize on PhonePe’s soaring operational revenues (₹7,631+ Cr in FY25) and its rapidly expanding ecosystem spanning merchant Soundboxes, Indus Appstore, Pincode (ONDC), insurance broking, and wealth management (Share.Market).
Founded in December 2015 by former Flipkart executives Sameer Nigam, Rahul Chari, and Burzin Engineer, PhonePe pioneered UPI payments just months ahead of the historic November 2016 demonetization wave. Operating with ruthless technological reliability and user-centric simplicity, PhonePe went on to achieve what few consumer internet platforms globally have accomplished: outcompeting deep-pocketed multinational rivals including Google Pay, WhatsApp Pay, and early pioneer Paytm to secure an undisputed, quasi-monopolistic ~48% market share in UPI transaction volume.
To pave the way for a domestic listing on Indian exchanges, PhonePe executed an audacious, multi-step structural reorganization. In late 2022, the company completed a complete legal separation from former parent Flipkart, establishing Walmart as its direct majority owner. More remarkably, PhonePe undertook a complete corporate redomiciliation from Singapore back to India—a bold decision that incurred an extraordinary ₹8,000+ Crore ($1 Billion) tax payment to the Indian exchequer. By legally domiciling in Bengaluru, PhonePe eliminated cross-border corporate governance hurdles, positioning itself as a genuinely Indian-domiciled corporate powerhouse perfectly suited for SEBI approval and domestic retail investor participation.
Based on disclosures synthesized from investment banking mandates, regulatory records, and Zerodha’s Official PhonePe IPO Portal, the core offering metrics governing the prospective listing are structured as follows:
| Parameter | Official Details & Market Intelligence |
|---|---|
| Company Name | PhonePe Limited |
| Corporate Status | Upcoming Mainboard Public Issue |
| Majority Shareholder & Promoter | Walmart Inc. (~85% economic interest) |
| Key Executive Leadership | Sameer Nigam (Founder & CEO), Rahul Chari (Co-Founder & CTO) |
| Estimated Issue Size | ₹13,500 Crore ($1.6 Billion) |
| Target Equity Valuation | Up to $15 Billion (₹1,25,000 Crore) |
| Offering Composition | Mix of Fresh Primary Growth Capital + Secondary Offer for Sale (OFS) |
| Key Strategic & Institutional Investors | General Atlantic, Microsoft, Tencent, Qatar Investment Authority (QIA), Tiger Global |
| Cumulative Capital Invested | Over ₹18,000 Crore to date |
| UPI Volume Market Share | 47.8% to 50.0% (Undisputed #1 in India) |
| Registered User Base | Over 590 Million Verified Users |
| Active Merchant Network | 40+ Million Offline Stores & Online Merchants |
| Daily Online Transactions | 310+ Million Transactions per Day |
| Proposed Listing Venues | BSE (Bombay Stock Exchange) & NSE (National Stock Exchange) |
| Investment Banking Mandates | Morgan Stanley, Goldman Sachs, Citigroup, JP Morgan, Kotak Mahindra Capital |
| Tracking Portal | Zerodha PhonePe IPO Tracking Page |
A common misconception among retail investors is that PhonePe is strictly a peer-to-peer (P2P) money transfer application that earns zero revenue due to the Indian government’s zero-MDR (Merchant Discount Rate) policy on UPI. In reality, PhonePe has constructed a highly monetized, multi-layered financial conglomerate that extracts recurring revenues across diversified consumer, merchant, and institutional touchpoints:
PhonePe’s audited financial disclosures demonstrate an extraordinary inflection point in revenue monetization. While early years required heavy marketing customer-acquisition burn, the platform’s operational scale is now generating compounding operational leverage:
| Key Financial Indicator | FY2024 (March 2024) | FY2025 (March 2025) | H1 FY2026 (Sept 2025 – 6M) |
|---|---|---|---|
| Operational Revenue | ₹5,722.20 Crore | ₹7,631.38 Crore (+33.4%) | ₹4,174.51 Crore (Annualized ₹8,350+ Cr) |
| Profit / (Loss) After Tax (PAT) | (₹1,996.17 Crore) | (₹1,727.41 Crore) | (₹1,444.42 Crore) |
| Consolidated Total Assets | ₹12,706.48 Crore | ₹18,205.23 Crore | ₹23,178.95 Crore |
| EBITDA ex-ESOP (Core Payments) | Near Break-even | Operationally Profitable | Positive Free Operating Cash Flow |
| Cash & Strategic Capital Reserves | ₹5,500+ Crore | ₹7,200+ Crore | ₹8,000+ Crore Fortress Reserves |
| External Debt on Balance Sheet | Zero Debt | Zero Debt | Zero Corporate Debt |
Crucially, a significant portion of PhonePe’s headline net accounting losses is attributable to non-cash Employee Stock Ownership Plan (ESOP) expenses associated with executive retention and its corporate migration from Singapore. On an adjusted operational EBITDA basis excluding non-cash ESOP charges, PhonePe’s standalone core payments entity has already crossed into operating profitability, powered by sticky Soundbox subscriptions and expanding financial service cross-selling margins.
Why has PhonePe succeeded where global tech giants have faltered? The platform possesses distinct structural moats that make user displacement virtually impossible for competitors:
To contextualize PhonePe’s prospective $15 Billion valuation, Dalal Street analysts benchmark its operating metrics against domestic and global fintech leaders:
| Comparative Parameter | PhonePe Limited | One97 Communications (Paytm) | PB Fintech (Policybazaar) | Block Inc. (Square / Cash App) |
|---|---|---|---|---|
| UPI Volume Market Share | ~48.0% (Dominant #1) | ~7.0% to 8.5% (#3) | N/A (Pure Insurance) | N/A (US / Global) |
| Registered Consumer Base | 590+ Million Users | ~320+ Million Users | ~75+ Million Users | ~56+ Million Cash App Users |
| Merchant Touchpoints | 40+ Million Merchants | ~38+ Million Merchants | Direct Aggregator | ~4+ Million Merchants |
| FY25 Annual Revenue | ₹7,631.38 Crore | ~₹6,500 Crore (Post-PPBL) | ~₹3,437 Crore | $21.9 Billion |
| Regulatory Model | Pure TPAP / Zero Bank Risk | Former Payments Bank (PPBL) | Direct Insurance Broker | Bank Holding Co (Industrial) |
| Target / Listed Market Cap | ₹1,25,000 Crore ($15B Est.) | ~₹45,000 Cr – ₹52,000 Cr | ~₹80,000 Cr – ₹85,000 Cr | ~$45.0 Billion |
| Promoter / Anchor Backing | Walmart Inc. (Retail Titan) | Antfin, SoftBank (Exiting) | Institutional / Dispersed | Jack Dorsey / Public Float |
While Paytm historically commanded the lead in offline soundbox deployment, PhonePe’s decisive capture of UPI market share, pristine regulatory record, and Walmart’s stewardship position it to trade at a substantial premium to One97 Communications upon listing.
The prospective PhonePe IPO represents an epochal moment for Indian capital markets. In a world where digital payments have emerged as essential public infrastructure, PhonePe is the unrivaled gatekeeper of Indian retail commerce.
Editorial Verdict: Landmark Bellwether Asset on Digital India
Unlike speculative fintech startups, PhonePe commands 48% of national UPI volumes, generates over ₹7,600+ Crore in annual revenue, and operates backed by the financial fortress of Walmart. With operational losses narrowing sharply, Soundbox SaaS recurring revenues multiplying, and high-margin lending distribution accelerating, PhonePe offers domestic institutional and retail investors an irreplaceable gateway to India’s multi-decade cashless consumption boom. Investors should monitor formal Draft Red Herring Prospectus (DRHP) filings for final valuation bands, promoter dilution ratios, and anchor allocations.
Please read this regulatory disclosure carefully:
1. Journalistic & Informational Purpose: The analysis, figures, estimates, Grey Market Premiums (GMP), and financial commentary regarding the prospective PhonePe IPO published on Udaipur Mirror are strictly for general informational, educational, and journalistic purposes.
2. Non-SEBI Registered: Udaipur Mirror, its editorial authors, and parent entity are NOT SEBI-registered investment advisors, portfolio managers, or research analysts. Nothing contained herein constitutes financial advice, stock recommendations, or an offer to solicit securities transactions.
3. Unofficial Estimates: Details regarding issue size (₹13,500 Cr), valuation ($15B), and timelines are derived from official media disclosures, investment banking reports, and Zerodha IPO listings; final parameters are subject to formal DRHP submission and regulatory clearance by SEBI.
4. Capital Risk Warning: Investments in equities, public offerings, and capital markets carry high risk of loss of principal. Readers must conduct independent financial due diligence and consult certified financial advisors before committing capital. Udaipur Mirror disclaims any liability for investment decisions.
Add Udaipur Mirror as a preferred source on Google to see more of our travel guides in your AI overviews.


[…] PhonePe IPO Date, Price, GMP, Review, Details — ₹13,500 Cr fintech mega-issue, $15B valuation, Walmart backing & 48% UPI market dominance. […]